Key takeaways
Estate planning is an important part of comprehensive financial planning, not something reserved only for wealthy or older families.
Without appropriate planning, assets governed by intestacy may be distributed according to state law rather than your personal wishes.
Reviewing beneficiary designations and organizing financial accounts are important parts of estate planning alongside creating a will.
Regular reviews, especially after major life events, can help keep your estate plan aligned with your current family, finances, and intentions.
Estate planning can come across as something reserved solely for ultra wealthy families with complicated finances. This makes sense, as generally when you hear the word “estate” you may think of a gated, multi-acre property with a mega mansion in the middle. In reality, this is not necessarily the case. If you own a home, maintain investment or retirement accounts, have money in the bank, own a business, or have children who depend on you, there are important financial and personal decisions worth planning for.
That is the exact purpose an estate plan serves. It creates a framework for how those decisions should be handled if you're no longer able to make them yourself. It can document your wishes, help organize your financial affairs, identify who should act on your behalf, and provide greater clarity for the people you leave behind. Without that planning, decisions may instead be governed by state law, existing beneficiary designations, account ownership, and other legal arrangements that don't necessarily reflect your intentions for your family or wealth.
This guide walks through what actually happens when there's no estate plan in place. It covers which assets may be affected, along with why putting a plan together is a natural extension of the financial planning you're likely already doing, not a separate task reserved for later in life.
Why Estate Planning Matters?
Estate planning is about more than deciding who receives your assets after you die. A comprehensive plan can also identify who is authorized to make financial or healthcare decisions on your behalf. It can document your wishes for minor children and provide instructions for handling your financial affairs.
For parents, estate planning is one part of preparing for a child's long-term future. Families may already be investing for college, building savings, or making other financial decisions on their children's behalf. An estate plan helps address how those responsibilities and intentions should be handled if a parent is no longer able to manage them.
Truthfully, every adult who owns assets has an estate. That might include bank accounts, investments, retirement savings, real estate, business interests, or other property. Estate planning isn't limited to people who consider themselves wealthy.
Planning ahead can also provide clarity for loved ones during an already difficult time. Instead of leaving family members to determine your intentions on their own, an estate plan creates a framework for the decisions you've already made. It connects the wealth you're building today with the people and priorities you want it to support in the future.
What Happens When You Die Without an Estate Plan?
When a loved one passes, it’s important to know what happens without a will having been created beforehand. When someone dies without a valid will, they are considered to have died intestate. State law then generally determines who inherits assets that become part of the probate estate. Instead of following instructions left by the individual, the estate is distributed according to a predetermined legal framework. The specifics vary by state. Each state has its own intestacy laws that determine which family members inherit what and how the estate is handled. Because these laws serve as a general default, the outcome may not reflect what the individual or family would have chosen. For Muslim families, it may also differ from their personal or religious intentions.
Furthermore, not every asset is necessarily distributed through intestacy. Retirement accounts, jointly owned property, and certain financial accounts may transfer according to beneficiary designations or ownership arrangements. This is one reason estate planning involves more than creating a will. It’s important to note that intestacy and probate laws can be complex and vary significantly by state. That is why it is recommended to consult with an estate planning attorney to help you understand how the laws where you live apply to your family and financial circumstances.
What Assets Could Be Affected?
This question is of great importance, as different assets can follow different rules when someone passes away. Some may become part of the probate estate, while others may transfer directly to a named beneficiary or surviving owner. For parents, these decisions are also part of a broader responsibility to plan for their children's future. That can include documenting wishes for minor children, determining how assets should eventually pass to them, and considering financial tools such as custodial investment accounts.
Understanding how your accounts and property are structured is therefore an important part of estate planning. A comprehensive plan considers not only who may eventually receive your assets, but also how different types of property are legally structured and transferred.
- Investment accounts: Individually owned brokerage accounts may become part of the estate unless another transfer arrangement is in place. Some accounts allow investors to name a transfer-on-death beneficiary, which can affect how the assets pass.
- Retirement accounts: Accounts such as 401(k)s and IRAs generally allow you to name beneficiaries. These designations can determine who receives the account after your death, making it important to keep them current as your family circumstances change.
- Bank accounts: Individually owned bank accounts may become part of the estate. Accounts with joint owners or valid payable-on-death designations may transfer differently.
- Real estate: How property transfers can depend on how it is titled, whether it is jointly owned, and the estate planning arrangements in place.
- Business interests: Ownership in a business can create additional estate planning considerations. Operating agreements, succession plans, and the structure of the business may all affect what happens to an ownership interest.
Because each asset may be handled differently, organizing your accounts is only one part of the process. For Muslim families, estate planning can also create an opportunity to consider how those financial decisions align with personal and Islamic values.
Why Estate Planning is Important for Muslim Families?
For Muslim families, estate planning can involve considerations beyond determining who receives particular assets. It provides an opportunity to document your intentions, prepare for the needs of loved ones, and consider how your financial legacy can reflect the values that guide other areas of your life.
This can be especially important when personal or religious wishes may not align with the default rules that apply without a plan. Families may want to document those wishes in a way that is legally valid in the U.S. while also reflecting religious values where appropriate and legally permissible. Doing so can require coordinating financial and legal planning with Islamic considerations around inheritance and legacy.
Because this intersection involves both U.S. law and matters of religious guidance, seeking appropriate professional advice is important. An estate planning attorney can help address the legal structure of a plan, while a qualified religious scholar can provide guidance on Islamic inheritance principles. This article provides general educational information rather than legal or religious guidance for any individual's circumstances.
Common Estate Planning Misconceptions
Estate planning can often be delayed because it feels unnecessary until one reaches a certain age or level of wealth. In truth, some of the most common reasons for putting it off are based on certain misconceptions about the purpose an estate plan actually serves. Addressing them and understanding these distinctions can make estate planning feel less like something to postpone and more like a part of managing the financial responsibilities one already has.
- “I’m too young.” Estate planning isn't only about preparing for death. Documents such as powers of attorney and healthcare directives can establish who is authorized to act on your behalf if you're unable to make certain decisions yourself.
- “I don't have enough money.” You don't need substantial wealth to have an estate. Bank accounts, investments, retirement savings, real estate, business interests, and other property can all create decisions worth planning for.
- “Everything automatically goes to my family.” Without appropriate planning, assets don't necessarily pass according to your personal wishes. State intestacy laws, account ownership, and other legal arrangements can influence who ultimately receives them.
- “Beneficiary forms are enough.” Beneficiary designations are important, but they only address certain assets. They don't replace other components of an estate plan, such as a will, powers of attorney, healthcare directives, or planning for minor children.
The Core Components of an Estate Plan
An estate plan can include several documents and financial arrangements that serve different purposes. While the appropriate structure depends on personal circumstances, there are a handful of core components to consider:
- A will: A will provides instructions for distributing property governed by the document after your death. It can also address other important wishes, including the nomination of guardians for minor children.
- Beneficiary designations: Retirement accounts, life insurance policies, and certain financial accounts allow you to name beneficiaries who may receive those assets directly. Keeping these designations current is an important part of maintaining an estate plan.
- Powers of attorney: A power of attorney can authorize another person to handle certain financial or legal matters on your behalf if circumstances require it.
- Healthcare directives: These documents can record your healthcare wishes and identify who may make medical decisions on your behalf if you're unable to communicate those decisions yourself.
- Guardianship considerations: Parents of minor children can use estate planning to document who they would want to care for their children if they are no longer able to do so.
This should serve as a general overview rather than legal drafting guidance. Actually creating these documents in a way that’s valid and reflects your specific wishes requires working with a qualified estate planning attorney.
Estate Planning and Your Investment Portfolio
Estate planning and investment management aren't separate tracks. They work best in coordination with each other. Reviewing beneficiaries across your accounts, rather than assuming they were set correctly once and never need revisiting, is one of the simplest steps you can take.
It's also important to organize your financial accounts and document your assets clearly. Making this information easier for family members or an executor to locate can reduce unnecessary complications when those assets eventually need to be managed.
Just as your diversification strategy should evolve with your financial goals, your estate plan should evolve with your life. Major changes to your family, finances, or investments can be a reason to revisit both rather than treating either as a one-time setup.
When Should You Review Your Estate Plan?
An estate plan should evolve as your life changes. Even the most well structured plan can become outdated when your family, finances, or legal circumstances change significantly from when it was first created. This being the case, major life events can serve as a natural opportunity for thorough review. These events can include (but are not limited to):
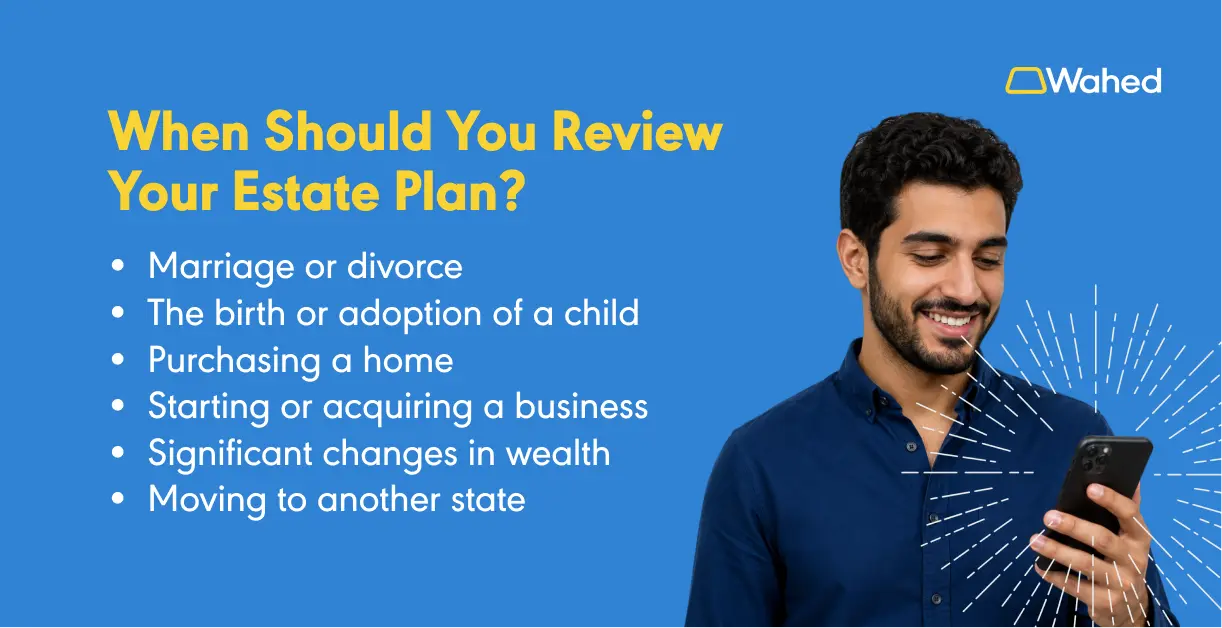
It's also worth reviewing your plan periodically even when there hasn't been a major life event. Beneficiaries, account ownership, financial priorities, and the assets you own can all change over time. A regular review helps ensure that your estate documents and financial accounts continue to reflect your current circumstances and intentions rather than decisions made years earlier.
Protect Your Family’s Financial Future
Estate planning is ultimately an extension of the same long-term financial stewardship that goes into building wealth, investing for the future, and reviewing your zakat strategy. Taking the time to organize your accounts, document your wishes, and put a plan in place isn't about dwelling on worst-case scenarios. It's about responsible, thoughtful planning that protects the people who matter most and helps build a lasting legacy.
Frequently asked questions
Estate planning isn't determined by age alone. Having assets, dependents, or people you want to make financial or healthcare decisions on your behalf can all make planning relevant. Starting earlier also allows your plan to evolve as your life and finances change.
Not necessarily. Some assets, such as retirement accounts with valid beneficiary designations, may transfer according to those designations rather than instructions in a will. Reviewing your full financial picture with a qualified professional can help clarify how individual assets may be handled.
Major life events such as marriage, divorce, the birth or adoption of a child, a home purchase, relocation, or a significant change in wealth are good reasons to review your plan. Periodic reviews can also help identify outdated documents, beneficiaries, or account information.
Retirement accounts generally allow you to name beneficiaries who may receive the assets after your death. Reviewing these designations and keeping them current is an important part of coordinating your retirement accounts with your broader estate plan.
Muslim families may choose to coordinate their estate planning with their religious values where legally appropriate. Because this can involve both U.S. law and Islamic inheritance considerations, families may benefit from working with a qualified estate planning attorney and, where appropriate, a knowledgeable religious advisor.
Wahed Invest LLC (Wahed) is a U.S. Securities and Exchange Commission (SEC) registered investment advisor. Wahed Invest provides brokerage services to its clients through its brokerage partner Apex Clearing Corporation, a member of NYSE - FINRA - SIPC and regulated by the SEC and the Commodity Futures Trading Commission. Registration does not imply a certain level of skill or training. Wahed does not intend to offer or solicit anyone to buy or sell securities in jurisdictions where Wahed is not registered or a region where an investment practice like this would be contrary to the laws or regulations. Any returns generated in the past do not guarantee future returns. All securities involve some risk and may result in loss. Any performance displayed in the advertisements or graphics on this site are for illustrative performances only.
Wahed does not provide legal or tax advice and this should not be considered tax advice. Diversification does not guarantee a profit or protect against loss.
Consult with your legal, tax and financial advisors before implementing any part of overall plans or estate planning.